Image source: AI-generated
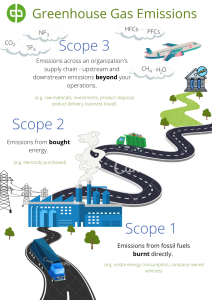
One of the central concepts in carbon accounting is the classification of emissions into three categories:
- Scope 1: Direct Emissions: Emissions from sources owned or controlled by the company. Example: fuel combustion in company facilities or vehicles.
- Scope 2: Indirect Energy Emissions: Emissions from purchased electricity, heat or steam. Reflects energy consumption rather than direct production.
- Scope 3: Value Chain Emissions: All other indirect emissions across the value chain. Includes suppliers, transportation, product use and disposal.
Why Scope 3 Matters:
Scope 3 emissions often represent the largest share of a company’s total footprint—in some sectors exceeding 70–90%. Yet they are also the most difficult to measure due to:
- Data dependency on suppliers and partners.
- Use of estimates and modelling
- Lack of standardised methodologies
Because of this complexity, companies may underreport, omit or selectively disclose Scope 3 emissions—making it a critical area for scrutiny.